
Building a startup requires more than a strong idea.
At some point, most founders need money to develop a product, hire employees, acquire customers, purchase equipment, expand infrastructure, or simply keep the company operating while revenue grows.
The difficult question is not whether funding exists.
It is deciding which type of startup funding makes sense for your company, stage, risk level, and growth strategy.
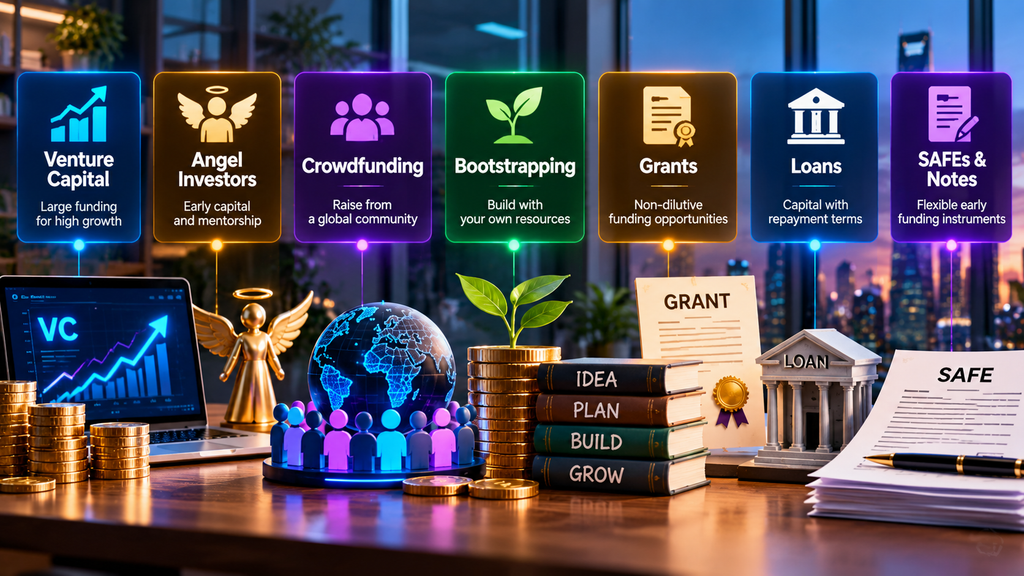
In 2026, founders can choose from bootstrapping, friends and family, angel investors, accelerators, venture capital, crowdfunding, business loans, grants, strategic investors, and other financing structures.
The market is also unusually uneven.
PitchBook and the National Venture Capital Association reported that U.S. startups raised more than $400 billion during the first half of 2026, but much of that capital was concentrated in AI companies and very large financing rounds.
At the earliest stages, Carta reported $3.19 billion invested through more than 11,500 pre-seed instruments in Q2 2026, with an average instrument size of approximately $276,000. AI startups captured about half of pre-seed dollars during the first half of the year.
This guide explains the major forms of startup funding in 2026, how they work, their advantages and disadvantages, and when each option may make sense.
Funding rules, securities laws and tax requirements vary by country, so founders should obtain professional legal and financial advice before completing a financing transaction.
Table of Contents
Startup Funding in 2026: Quick Overview
| Funding Method | Gives Up Equity? | Repayment Required? | Typical Fit |
|---|---|---|---|
| Bootstrapping | No | No | Very early startups and capital-efficient businesses |
| Friends & Family | Sometimes | Sometimes | Early validation and small initial rounds |
| Angel Investors | Usually | No | Pre-seed and seed startups |
| Accelerators | Usually | No | Early startups needing capital, mentorship and networks |
| Venture Capital | Yes | No | High-growth, scalable startups |
| Reward Crowdfunding | No | No | Consumer products and creative projects |
| Equity Crowdfunding | Yes | No | Startups raising from a broad investor base |
| Business Loans | No | Yes | Businesses with repayment capacity |
| Grants | No | Usually no | Research, innovation and targeted programs |
| Strategic Investors | Usually | No | Companies seeking capital plus industry access |
| Revenue-Based Financing | Usually no | Yes, tied to revenue | Companies with predictable recurring revenue |
1. Bootstrapping — Funding the Startup Yourself
Bootstrapping means building the company primarily with the founder’s own resources and revenue generated by the business.
That might involve personal savings, consulting income, early customer payments, retained profits, or keeping operating costs extremely low.
The biggest advantage is control.
Founders do not have to negotiate valuation, issue shares, create investor reporting processes, or give another party influence over major business decisions.
The U.S. Small Business Administration describes self-funding as a method that lets entrepreneurs retain control while taking the financial risk themselves.
Bootstrapping can also force discipline.
When capital is limited, founders tend to focus closely on customers, pricing, revenue, and products people are actually willing to buy.
The disadvantage is that growth may be slower.
A company competing in AI infrastructure, biotechnology, advanced hardware, or another capital-intensive field may simply require more money than its founders can reasonably provide.
Personal financial risk is another important consideration.
Founders should avoid putting money at risk that they cannot afford to lose.
Best fit: Capital-efficient software, services, consulting, e-commerce and businesses capable of generating early revenue.
2. Friends and Family — Early Capital From Personal Networks
Friends-and-family financing often appears before professional investors are willing to participate.
A founder may raise a relatively small amount from people who already know and trust them.
This capital can help build an initial product, validate demand, form the company, or reach enough progress to approach angel investors.
However, informal funding should not mean informal documentation.
The parties should clearly understand whether the money is:
- A gift
- A loan
- Equity
- A SAFE
- A convertible note
- Another legally documented investment
Mixing personal relationships and money can create serious problems if expectations are unclear.
A founder should never imply that startup investment is safe or guaranteed.
Startups can fail, and early investors may lose their entire investment.
Best fit: Very early businesses needing modest capital before institutional fundraising.
3. Angel Investors — Early Funding Plus Experience
Angel investors are individuals who invest their own money into private companies.
They often participate during pre-seed or seed stages, before traditional venture funds become interested.
Angel checks can range widely.
Some investors make relatively small individual investments, while experienced angels or organized groups may participate in much larger rounds.
The value of a good angel investor can extend beyond capital.
An experienced investor may help with:
- Recruiting
- Introductions to customers
- Future investors
- Product strategy
- Industry relationships
- Fundraising preparation
Angel capital normally comes in exchange for ownership or a security that may later convert into ownership.
Founders should therefore evaluate an angel investor based on more than the size of the check.
The relationship may continue for years.
Best fit: Pre-seed and seed companies with promising products but limited operating history.
4. Accelerators and Incubators — Capital Plus a Network
Startup accelerators combine several resources.
A typical program may provide capital, mentorship, investor introductions, workshops, technical support and access to a founder community.
Accelerators usually operate over a defined period and may conclude with a demo day or investor presentation.
The company may give up equity or agree to investment terms in exchange for participation.
The strongest accelerators can be valuable because they compress months of networking and learning into a much shorter period.
However, founders should not assume that every accelerator is equally useful.
Before joining one, examine:
- The investment terms
- Alumni outcomes
- Mentor quality
- Investor network
- Industry specialization
- Time commitment
- Reputation among previous founders
An accelerator should create value beyond simply placing its logo on the startup’s website.
Best fit: Early-stage founders who need mentorship, network access and help preparing for institutional fundraising.
5. Venture Capital — Funding for Aggressive Growth
Venture capital firms invest money from funds that are typically backed by institutional and professional investors.
For examples of companies attracting attention in the current AI market, see our guide to AI startups to watch in 2026.
VC financing is designed primarily for companies that could become significantly larger.
Investors generally look for businesses with characteristics such as:
- Large potential markets
- Strong growth
- Scalable business models
- Defensible technology or advantages
- Experienced teams
- The potential for a major acquisition or public offering
Venture capital can provide much more money than most founders could obtain through bootstrapping or small angel rounds.
It can fund rapid hiring, international expansion, research, infrastructure, marketing and acquisitions.
But venture capital has a cost.
Founders give up ownership and usually accept additional governance rights for investors.
VC-backed companies may also face expectations for aggressive growth and eventual liquidity.
The 2026 venture market is particularly important to understand.
Headline investment numbers are extremely high, but PitchBook-NVCA data shows that capital remains heavily concentrated in AI and mega-rounds rather than being distributed evenly across startups.
Carta’s data similarly shows a divergence between stages: total funding increased during the first half of 2026, while seed funding on its platform declined compared with the same period in 2025.
A record venture market therefore does not mean fundraising is easy for every company.
Best fit: Startups targeting rapid growth, very large markets and potentially significant exits.
6. SAFEs and Convertible Notes — How Early Investments Are Structured
SAFEs and convertible notes are not separate sources of money.
They are financial instruments frequently used when raising early-stage capital from angels, seed investors and other investors.
SAFE
SAFE stands for Simple Agreement for Future Equity.
A SAFE gives the investor rights to receive equity under specified future conditions.
Unlike a traditional loan, a SAFE generally does not carry interest or a maturity date.
Convertible Note
A convertible note is debt that is designed to convert into equity later.
It generally includes:
- An interest rate
- A maturity date
- Conversion provisions
- Often a valuation cap or discount
In 2026, SAFEs dominate U.S. pre-seed financing within Carta’s dataset.
Carta reports that SAFEs represented 93% of pre-seed rounds and 95% of pre-seed capital in Q2 2026.
Founders should still understand the dilution created by multiple SAFEs.
A document that appears simple when signed can become more complicated when several instruments convert during a priced equity round.
Best fit: Early-stage fundraising where founders and investors want to postpone a formal priced valuation.
7. Reward-Based Crowdfunding — Customers Fund the Product
Reward crowdfunding allows supporters to contribute money without receiving ownership in the company.
Instead, they may receive:
- The product
- Early access
- Special editions
- Discounts
- Experiences
- Other rewards
Kickstarter is one of the best-known examples.
It uses an all-or-nothing funding model: creators receive the pledged funds only when the campaign reaches its funding goal. Backers do not receive equity in the project.
For product startups, reward crowdfunding can do more than provide capital.
It can test whether real customers are willing to pay.
A successful campaign can validate demand before large manufacturing commitments are made.
However, crowdfunding introduces operational responsibilities.
A startup must accurately estimate production, shipping, taxes, fees and delivery timelines.
Raising money successfully and then failing to deliver the promised product can seriously damage a brand.
Best fit: Consumer products, hardware, games, creative businesses and products with a strong community story.
8. Equity Crowdfunding — Raising Capital From the Crowd
Equity crowdfunding is fundamentally different from reward crowdfunding.
Investors provide capital in exchange for securities rather than receiving only a product or reward.
In the United States, Regulation Crowdfunding allows eligible companies to raise securities financing through an SEC-registered broker-dealer or funding portal.
The current Regulation Crowdfunding framework permits an issuer to raise up to $5 million in a 12-month period, subject to regulatory requirements and investor protections.
The SEC issued additional interpretations of Regulation Crowdfunding during 2026, including guidance on the rolling 12-month calculation and ongoing reporting.
Equity crowdfunding can expose a company to investors beyond traditional venture networks.
It can be particularly interesting for startups that already have an enthusiastic customer or user community.
However, securities crowdfunding comes with legal, disclosure, reporting and administrative obligations.
Founders should work with qualified securities professionals rather than treating an equity campaign like a normal product crowdfunding page.
Best fit: Startups with strong communities that want to broaden access to their fundraising round.
9. Business Loans — Capital Without Giving Up Ownership
Debt financing works differently from equity.
The lender provides money, and the company agrees to repay the loan according to defined terms.
Founders do not normally give up equity simply because they borrow money.
This can make debt attractive to entrepreneurs who want to preserve ownership.
The tradeoff is obvious:
The loan must be repaid whether the startup succeeds or struggles.
Banks and other lenders commonly evaluate:
- Revenue
- Cash flow
- Credit history
- Collateral
- Business history
- Ability to repay
That can make conventional loans difficult for very early startups with no revenue.
In the United States, SBA-backed programs include 7(a), 504 and microloans. SBA microloans can provide up to $50,000, while other programs are designed for larger financing requirements.
In July 2026, the SBA also announced that eligible borrowers could combine 7(a) and 504 financing for up to $10 million in SBA-backed capital.
Programs vary substantially by country.
Best fit: Businesses with predictable revenue, assets or a clear capacity to repay debt.
10. Grants and Startup Competitions — Non-Dilutive Funding
Grants are attractive because they often do not require founders to give up ownership.
They may be offered by:
- Governments
- Universities
- Research organizations
- Foundations
- Economic development agencies
- Corporate programs
Grant funding is often targeted.
Programs may focus on fields such as:
- Scientific research
- Healthcare
- Clean energy
- Manufacturing
- Defense
- Agriculture
- Education
- Regional development
Startup competitions may provide similar non-dilutive awards.
The major disadvantage is competition and restrictions.
Applications can require significant documentation, and funds may be limited to specific uses.
Founders should also be cautious of websites that promise guaranteed government grants in exchange for fees.
Use official government or institutional sources whenever possible.
Best fit: Research-heavy companies, deep technology, science-based startups and businesses aligned with targeted public programs.
11. Strategic and Corporate Investors — Capital Plus Market Access
Large companies sometimes invest directly in startups.
This can happen through corporate venture capital funds or strategic investments from operating businesses.
A strategic investor may bring more than money.
Potential benefits include:
- Distribution
- Manufacturing capability
- Technology
- Industry knowledge
- Customers
- Supply-chain access
- Geographic expansion
However, strategic capital can introduce conflicts.
A close relationship with one large corporation may discourage its competitors from becoming customers or investors.
Founders should examine any exclusivity, commercial obligations, intellectual property provisions and rights attached to the investment.
Best fit: Startups where an industry partner can accelerate distribution, product development or market entry.
12. Revenue-Based Financing — Repayment Linked to Revenue
Revenue-based financing sits somewhere between conventional debt and equity financing.
The company receives capital and agrees to repay based partly on revenue.
Instead of giving the investor permanent equity, the business typically makes payments until an agreed repayment amount has been reached.
This model can be attractive to companies with predictable recurring revenue.
Examples may include:
- SaaS
- E-commerce
- Subscription businesses
- Digital services
The advantage is ownership preservation.
The disadvantage is that ongoing repayments reduce cash available for growth.
Founders should compare the effective cost carefully with alternatives such as traditional debt or equity.
Best fit: Revenue-generating startups with predictable cash flow that want to avoid further equity dilution.
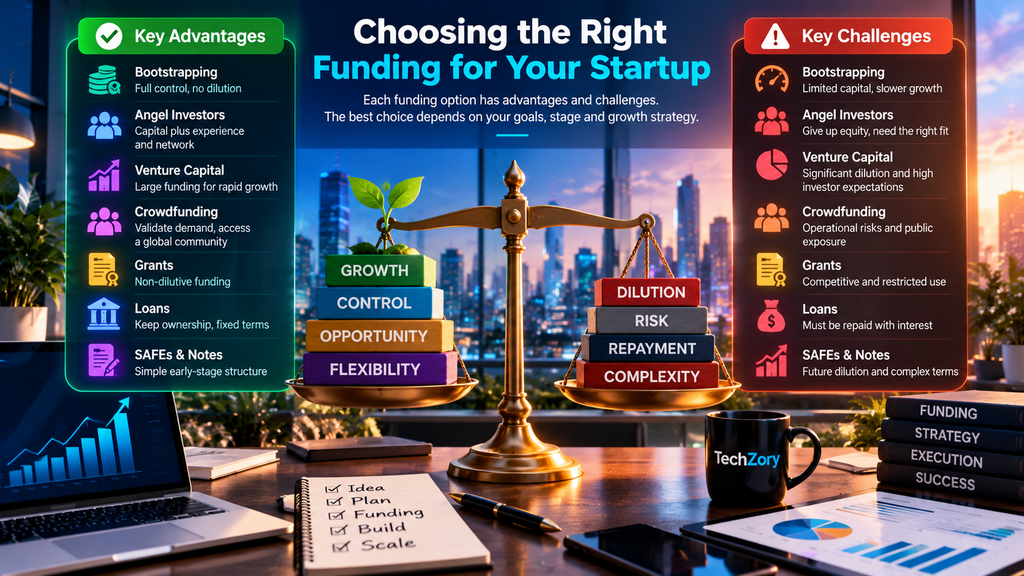
Quick Comparison of Startup Funding Options in 2026
No single financing method is appropriate for every startup.
Bootstrapping maximizes founder control but limits available capital.
Friends and family can provide early support but introduce personal relationship risk.
Angel investors provide capital and potentially useful experience.
Accelerators can combine small investments with mentorship and networks.
Venture capital can finance extremely rapid growth but creates significant dilution and investor expectations.
Reward crowdfunding can validate a consumer product without selling equity.
Equity crowdfunding expands the investor base but requires securities compliance.
Loans preserve equity but introduce repayment obligations.
Grants are non-dilutive but competitive and often restricted.
Strategic investors can provide industry access but may create commercial conflicts.
Revenue-based financing can preserve ownership, although repayment reduces future cash flow.
The right option depends on what the business is trying to accomplish.
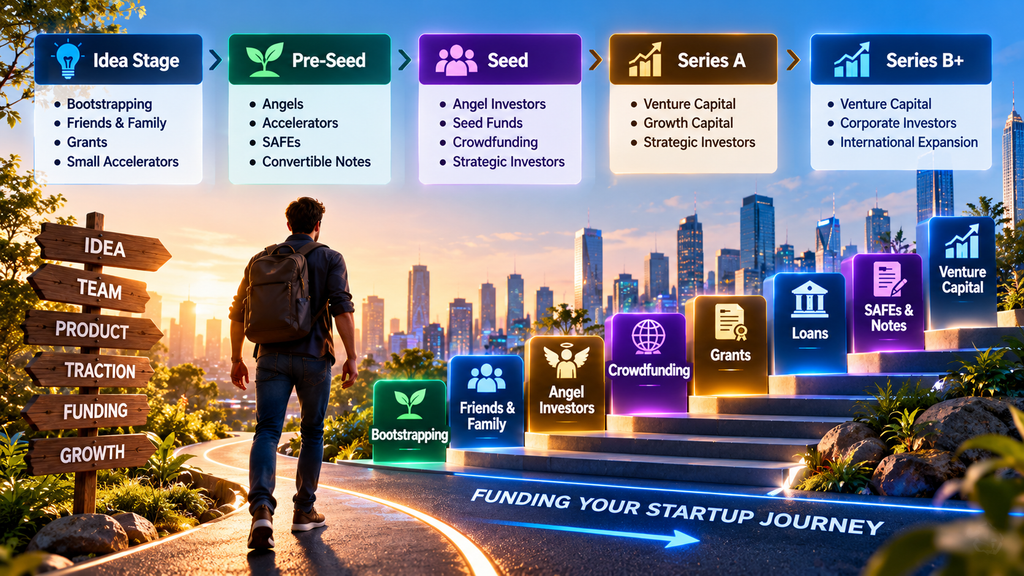
How Startup Funding Changes by Stage
Funding strategies often evolve as a company grows.
Idea Stage
At the idea stage, founders commonly depend on:
- Personal savings
- Side income
- Friends and family
- Grants
- Small accelerator programs
The goal is usually to demonstrate that the idea deserves further investment.
Pre-Seed
Pre-seed financing is typically used to build an initial team and product.
Common sources include:
- Founders
- Angels
- Accelerators
- Micro-VC funds
- SAFEs
- Convertible notes
Carta’s Q2 2026 data shows how heavily this stage now relies on SAFEs.
Seed
Seed funding generally supports:
- Product development
- Hiring
- Customer acquisition
- Early scaling
- Market validation
Angel investors, seed funds and venture firms may participate.
Series A
Series A investors generally expect stronger evidence of product-market fit and a credible scaling plan.
According to Carta’s Q2 2026 data, the median Series A round in its dataset was approximately $14.7 million, with a median post-money valuation of about $78.7 million.
These are benchmarks, not targets.
Startup financing varies dramatically by industry, geography, traction and market conditions.
Series B and Beyond
Later rounds typically fund larger expansion.
This might include:
- International growth
- Significant hiring
- Acquisitions
- New product lines
- Infrastructure
- Regulatory expansion
Investors also generally expect much more detailed financial and operational data.
Startup Funding Trends in 2026
One word describes the 2026 funding market particularly well:
Concentration.
Large amounts of capital are being invested, but not evenly.
PitchBook-NVCA reports record U.S. investment levels during the first half of 2026, while emphasizing that AI and rounds of $100 million or more account for a very large share of activity.
Carta sees a similar pattern at the earliest stages.
Its Q2 pre-seed report shows approximately the same total cash invested as a year earlier but spread across fewer financing instruments, pushing average check sizes upward.
AI also remains unusually important.
Around 49% of pre-seed dollars recorded by Carta during the first half of 2026 went to AI companies.
For founders outside the hottest sectors, these numbers provide an important warning:
Do not assume that record industry funding means every startup can raise easily.
Investor interest remains selective.
How Much Money Should a Startup Raise?
The answer should begin with the company’s plan, not the largest amount an investor is willing to provide.
Estimate how much money is required to reach the next meaningful milestone.
That milestone might be:
- Launching the product
- Reaching initial revenue
- Obtaining regulatory approval
- Achieving a customer target
- Building a manufacturing prototype
- Demonstrating product-market fit
- Reaching profitability
Then build a realistic budget.
Consider:
- Salaries
- Cloud infrastructure
- Product development
- Marketing
- Legal expenses
- Insurance
- Office expenses
- Equipment
- Taxes
- Regulatory requirements
- Unexpected costs
Founders should also consider runway.
Raising too little can force the company back into fundraising before it has made enough progress.
Raising far more than necessary may cause unnecessary dilution or encourage inefficient spending.
What Investors Look for in 2026
Different investors use different criteria, but several questions appear repeatedly.
Is the Problem Important?
Strong technology does not automatically create a strong business.
Investors want to understand who has the problem and why solving it matters.
Is the Market Large Enough?
Venture investors in particular need opportunities capable of producing very large outcomes.
Does the Product Have Traction?
Traction may include:
- Revenue
- Users
- Growth
- Retention
- Pilot customers
- Contracts
- Usage
- Technical milestones
Why This Team?
Founders should explain why their experience, insight or technology creates an advantage.
What Makes the Company Defensible?
Competition matters.
Potential advantages may include:
- Proprietary technology
- Data
- Network effects
- Distribution
- Brand
- Intellectual property
- Regulatory approvals
- Switching costs
How Will the Capital Be Used?
A fundraising plan should clearly connect capital to milestones.
Investors want to understand what changes after the money enters the company.
Equity Dilution and Founder Control
Equity financing does not require monthly repayment.
Instead, founders exchange part of the ownership of their company for capital.
This is dilution.
Suppose founders own 100% of a company before outside investment.
If investors purchase 20% of the company, the existing owners collectively hold 80% afterward, before considering other factors such as employee option pools.
Future rounds can create additional dilution.
Dilution is not automatically bad.
Owning a smaller percentage of a much more valuable company can be better than owning 100% of a company that cannot grow.
The important question is whether the capital and investor relationship create enough value to justify the ownership given up.
Preparing for a Fundraising Round
Founders should organize the company before approaching investors.
Common materials include:
- Pitch deck
- Financial model
- Cap table
- Product demonstration
- Market analysis
- Customer metrics
- Revenue information
- Incorporation documents
- Contracts
- Intellectual property documentation
- Data room
Founders preparing to scale should also review the best startup tools in 2026 for managing productivity, CRM, payments, design, automation, finance, and security.
The company should also understand its own metrics.
A founder should not discover basic revenue, runway or ownership information while answering investor questions.
Preparation also makes due diligence faster.
Common Startup Funding Mistakes
One common mistake is fundraising too early.
If a founder can reach a major milestone inexpensively, achieving it before fundraising may strengthen the company’s position.
Another mistake is choosing investors based only on valuation.
Investor reputation, behavior, network and expectations can matter for many years.
Founders also sometimes raise capital without understanding dilution.
This becomes particularly dangerous when multiple SAFEs, notes and option pools interact.
Another mistake is assuming that fundraising itself represents business success.
Capital is a resource.
It is not revenue, product-market fit or profitability.
Finally, founders should avoid building a business model that requires continuous financing simply to survive unless there is a credible reason future investors will continue supporting the company.
Bootstrapping vs. Venture Capital
This is not simply a question of which option is better.
The two approaches support different business strategies.
Bootstrapping favors:
- Control
- Capital efficiency
- Revenue discipline
- Slower sustainable growth
Venture capital favors:
- Speed
- Aggressive hiring
- Large markets
- Rapid expansion
- Significant investment before profitability
A profitable software company may have little reason to raise venture capital.
A semiconductor startup may have almost no practical way to bootstrap its development.
The funding model should match the economics of the business.
Crowdfunding vs. Angel Investment
Crowdfunding can be attractive when the company already has a community or a product that consumers can easily understand.
Angel investment may be more appropriate when the business is technical, difficult to explain publicly, or still requires substantial product development.
Reward crowdfunding can also provide market validation because supporters are effectively demonstrating demand.
Angel investors, however, may provide knowledge and introductions that a large group of crowdfunding backers cannot.
The two methods can also complement each other.
A successful crowdfunding campaign may help demonstrate traction before an angel or venture round.
Frequently Asked Questions
What is the best way to fund a startup in 2026?
There is no universal answer.
Bootstrapping works well for capital-efficient businesses, angels and accelerators can fit early-stage companies, venture capital suits high-growth startups, crowdfunding can work well for community-driven products, and debt may be appropriate for businesses with reliable repayment capacity.
What is bootstrapping?
Bootstrapping means funding a company primarily through the founders’ own resources and revenue generated by the business rather than relying heavily on external investors.
What is an angel investor?
An angel investor is an individual who invests their own capital into private companies, often during early startup stages.
What is venture capital?
Venture capital is professional investment into high-growth private companies, generally in exchange for equity and investor rights.
What is a SAFE?
A SAFE is a Simple Agreement for Future Equity.
It allows an investor to provide capital now in exchange for rights to receive equity under defined future conditions.
Are SAFEs common in 2026?
Yes, particularly at the U.S. pre-seed stage.
Carta reports that SAFEs represented 93% of pre-seed financing instruments in its Q2 2026 dataset.
Can startups raise money through crowdfunding?
Yes.
Reward crowdfunding allows supporters to fund projects without receiving equity, while securities crowdfunding can allow qualifying companies to raise investment capital under applicable securities regulations.
How much can a U.S. company raise through Regulation Crowdfunding?
Under the current U.S. Regulation Crowdfunding framework, eligible issuers can raise up to $5 million during a 12-month period, subject to the regulation’s requirements.
Do startups need venture capital?
No.
Many successful businesses are bootstrapped, financed through revenue, funded by loans, or built with relatively small amounts of outside capital.
Venture capital makes the most sense when large amounts of money can accelerate a scalable business opportunity.
Does raising money mean a startup is successful?
No.
Funding measures investors’ willingness to provide capital.
Long-term business success depends on factors such as product value, customers, revenue, costs, execution and sustainable economics.
Final Thoughts
Startup funding in 2026 offers founders more options than simply choosing between a bank loan and venture capital.
Bootstrapping provides control.
Friends and family can help a company take its first steps.
Angel investors can provide early capital and expertise.
Accelerators can add networks and mentorship.
Venture capital can fund aggressive expansion.
SAFEs and convertible notes can simplify early financing structures.
Reward crowdfunding can validate demand without selling equity.
Equity crowdfunding can connect companies with a broader investor base.
Loans preserve ownership but require repayment.
Grants can provide valuable non-dilutive capital.
Strategic investors can bring industry access.
Revenue-based financing can support companies with predictable sales while limiting equity dilution.
The most important decision is not how much money a startup can raise.
It is what kind of capital helps the company reach its next milestone without creating unnecessary risk, dilution or complexity.
In a 2026 funding market where enormous headline numbers coexist with strong concentration and selective investment, founders should build financing strategies around the economics of their own business—not around fundraising headlines.
Sources and Further Reading
- PitchBook & NVCA — Venture Monitor 2026
- Carta — State of Pre-Seed: Q2 2026
- Carta — SAFE Valuation Caps and Pre-Seed Financing in 2026
- Carta — Startup Fundraising and Round Benchmarks
- U.S. SEC — Regulation Crowdfunding
- U.S. SEC — Regulation Crowdfunding: Guidance for Issuers
- U.S. SEC — 2026 Regulation Crowdfunding Interpretations
- U.S. Small Business Administration — Fund Your Business
- U.S. Small Business Administration — Loans and Microloans
- U.S. Small Business Administration — Investment Capital and SBICs
- U.S. Small Business Administration — Grants and Additional Funding Opportunities
- Kickstarter — How Crowdfunding Works: A Guide for Creators